← Corporate Tax Services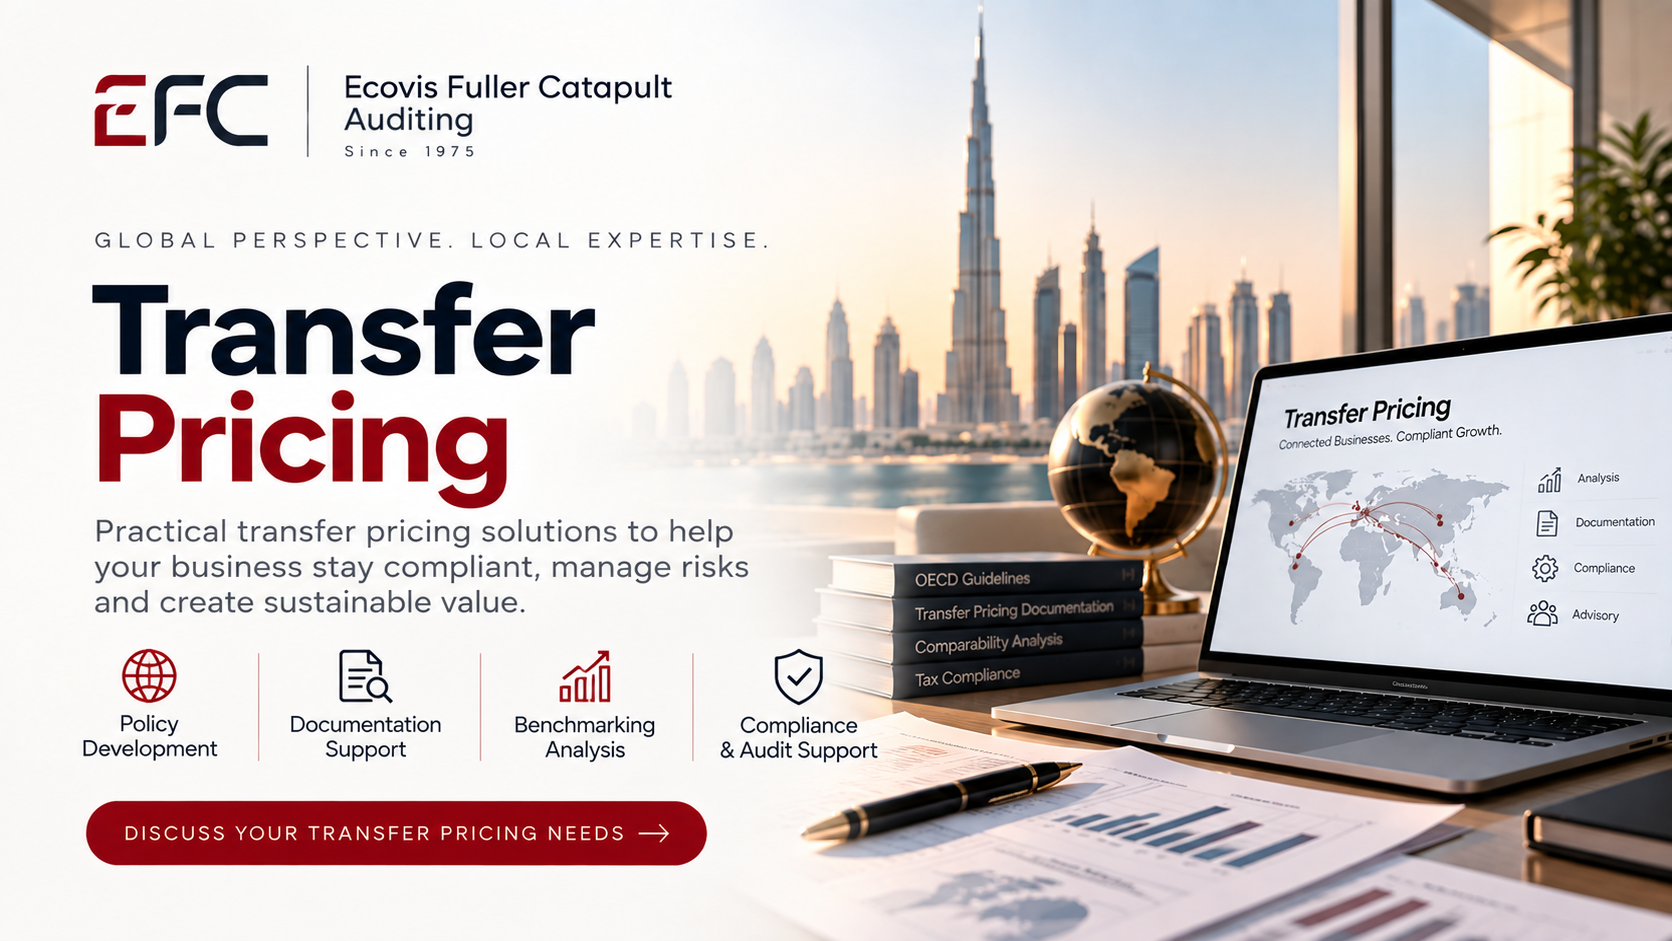
What is it?
The set of rules and analysis ensuring that transactions between related or connected parties are priced at arm's length for UAE Corporate Tax purposes, in line with OECD transfer pricing guidelines.
Transfer Pricing
Transfer pricing analysis and policy design to keep related-party transactions compliant with UAE arm's-length rules.
UAE Corporate Tax law requires transactions between related parties and connected persons to be priced as if they were between independent parties — the arm's length principle, based on OECD guidelines. This applies to intercompany sales, management fees, royalties, financing and cost-sharing arrangements, including cross-border transactions with related entities in India, the GCC or elsewhere. We benchmark your related-party pricing, design defensible transfer pricing policies, and align them with your group's global TP framework where one exists.
What is it?
The set of rules and analysis ensuring that transactions between related or connected parties are priced at arm's length for UAE Corporate Tax purposes, in line with OECD transfer pricing guidelines.
Who needs it?
Any UAE business with related-party or connected-person transactions — intercompany sales, loans, management fees, royalties or cost allocations — particularly groups with entities in India, other GCC states, or globally.
Any UAE business with related-party or connected-person transactions — intercompany sales, loans, management fees, royalties or cost allocations — particularly groups with entities in India, other GCC states, or globally.
Benefits
- Defensible, benchmarked pricing that withstands FTA scrutiny
- Alignment between UAE TP policy and your group's global framework
- Reduced risk of profit-shifting challenges and double taxation
- Clear intercompany agreements that match the actual pricing applied
Our Process
1. Map all related-party and connected-person transactions across the group
2. Select the appropriate transfer pricing method for each transaction type
3. Run a benchmarking study against comparable independent transactions
4. Design or refresh intercompany agreements to match the agreed pricing
Cost Factor ~ Driven by number and type of related-party transactions, availability of comparable benchmarking data, and whether a full study or a policy review is needed.
Timeline ~ A focused transaction review takes 2–3 weeks; a full benchmarking study across multiple transaction types typically takes 4–6 weeks.
FAQs
1. Does transfer pricing apply to small or single-owner UAE companies?
It can — the rules apply to transactions with any related party or connected person, including the owner personally, not just large multinational groups. Even a modest management fee or loan between related entities needs to be arm's length and, above certain thresholds, documented.
It can — the rules apply to transactions with any related party or connected person, including the owner personally, not just large multinational groups. Even a modest management fee or loan between related entities needs to be arm's length and, above certain thresholds, documented.
2. What counts as a "related party" under UAE Corporate Tax?
Related parties include entities under common ownership or control, individuals and their close family members holding an ownership interest, and partners in the same partnership, among other defined relationships. Connected persons (owners, directors, and their relatives) have a separate but related set of rules.
Related parties include entities under common ownership or control, individuals and their close family members holding an ownership interest, and partners in the same partnership, among other defined relationships. Connected persons (owners, directors, and their relatives) have a separate but related set of rules.
3. What happens if my transfer pricing isn't at arm's length?
The FTA can adjust your taxable income to reflect what an arm's-length price would have been, which can increase your tax liability plus penalties and interest. Contemporaneous documentation showing how pricing was determined is your primary defense if challenged.
The FTA can adjust your taxable income to reflect what an arm's-length price would have been, which can increase your tax liability plus penalties and interest. Contemporaneous documentation showing how pricing was determined is your primary defense if challenged.
Who needs it?
Contact us to discuss whether this fits your situation.
Our process
Every engagement starts with a scoping consultation — get in touch to discuss the steps involved.
Timeline
Varies by engagement scope — ask us for an estimate.
Cost factors
Fees depend on scope and complexity — contact us for a tailored quote.
Ready to talk?
Book a confidential consultation with one of our partners to discuss transfer pricing.
Book a ConsultationTrusted By
What Our Clients Say
“If you want a trustworthy and reliable company for your Accounting needs please choose Catapult Accounts. I have been with them for many years”
Ms. Donna Rayson
CEO · Seven oaks British Nursery